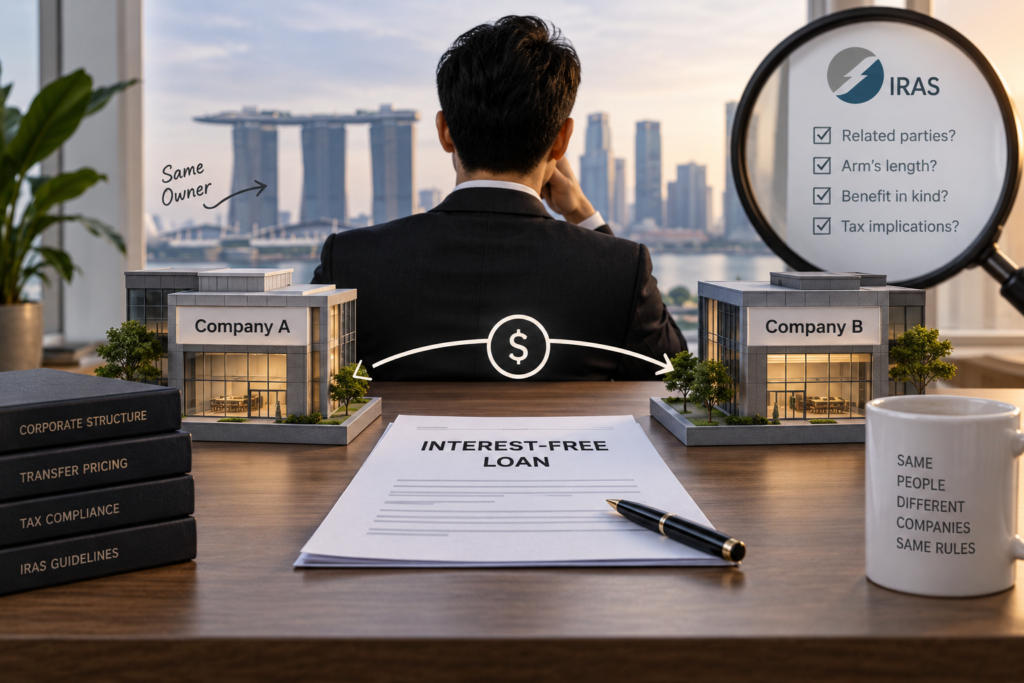
One Owner, Two Companies, One Interest-Free Loan. IRAS Has a View on That.
Here is a structure so common in Singapore that most owners never think twice about it.
You own two companies. One is cash-rich, one is growing. Money moves between them as needed — an interest-free loan here, some shared staff there, the occasional “management fee” that nobody ever sat down to price. The holding company pays for software the operating company uses. Nobody invoices anybody at “market rates,” because why would you charge yourself?
Under Singapore tax law, every one of those arrangements is a transfer pricing position — and IRAS has been clear for years about how it expects them to be handled. Since Year of Assessment 2019, the tax authority has had the power not only to adjust the taxable income of companies whose related-party dealings are not priced at arm’s length, but to add a flat 5% surcharge on the adjustment — payable even if the adjustment creates no extra tax.
Transfer pricing has a reputation as a multinational problem, all tax havens and billion-dollar disputes. The reality in Singapore is more mundane and much closer to home: the rules in Sections 34D and 34F of the Income Tax Act apply to every company that transacts with a related party — including the two-company family group, the operating company and its property-holding sibling, and, increasingly, the Singapore SME with a new Johor subsidiary.
This article explains what the rules actually require at each size of business, what changed for the YA 2026 filing now due on 30 November, and the handful of fact patterns where small groups most often get it wrong.
The Principle: Price It Like You Would With a Stranger
Singapore’s transfer pricing framework rests on one idea — the arm’s length principle, codified in Section 34D. Transactions between related parties must be priced as if the parties were independent businesses negotiating in the open market. “Related parties” broadly means entities under common control — two companies with the same owner, parent and subsidiary, and companies controlled by the same family.
The logic is straightforward. When both sides of a deal answer to the same owner, the price can be set to shift profit wherever it is most convenient — into the company with unused tax exemptions, out of the one facing a higher effective rate, or across a border entirely. The arm’s length principle removes that discretion for tax purposes: whatever you actually charged, IRAS assesses the transaction as if a market price had applied.
Crucially, the principle binds every company, at every size. The S$10 million threshold you may have heard about governs who must prepare formal documentation — not who must price at arm’s length. A S$2 million revenue company that routes profit to a related entity through an artificial fee is exposed to an adjustment and the 5% surcharge just as a S$200 million one is.
Who Must Prepare Formal Documentation — and What Changed for YA 2026
Formal, contemporaneous transfer pricing documentation (TPD) under Section 34F — a written analysis showing how each related-party transaction was priced and why that pricing is arm’s length — is required when a company’s gross revenue from trade or business exceeds S$10 million for the basis period, or when TPD was required for the immediately preceding period.
Even above S$10 million, the rules exempt transaction categories below set values. And here is the detail that matters for the return due in eight weeks: under the 2024 amendment to the TPD Rules, the exemption threshold for services, royalties, guarantees, rentals and other non-goods, non-loan categories rose from S$1 million to S$2 million per category, effective from YA 2026 — the filing due 30 November 2026. The thresholds now stand at:
- Purchases of goods from related parties: S$15 million
- Sales of goods to related parties: S$15 million
- Related-party loans: S$15 million (per the loans owed to / owed by categories)
- Services, royalties, rentals, guarantees and all other categories: S$2 million per category
A company above S$10 million in revenue whose related-party service charges run to S$1.4 million a year was caught under the old S$1 million threshold and is exempt under the new one — a genuine, and little-noticed, compliance easing for mid-sized groups. The reverse discipline also applies: these are per-category tests, so a group with S$12 million of related-party goods purchases and S$2.5 million of management fees must document both.
Three mechanics for those who are in scope. TPD must be contemporaneous — in place by the tax return filing date, not assembled after an audit letter arrives. It must be produced within 30 days of an IRAS request. And it can be refreshed once every three years where the facts have not materially changed, which substantially reduces the ongoing cost. Failure to prepare or retain TPD when required is an offence carrying fines of up to S$10,000 — but the real money is never the fine; it is the adjustment and surcharge that weak documentation invites.
One more number to keep separate: companies must also complete the Related Party Transactions declaration with Form C when the value of related-party transactions in the financial statements exceeds S$15 million. That disclosure threshold is a different S$15 million from the loan-exemption threshold above — conflating the two is a recurring error even among finance teams.
The 5% Surcharge: Why This Stopped Being Theoretical
Before 2019, an IRAS transfer pricing adjustment simply meant paying the tax you would have paid anyway. Since YA 2019, every upward adjustment under Section 34D carries a surcharge of 5% of the adjustment amount — not 5% of the tax, 5% of the adjustment — and it applies even where the adjustment produces no additional tax, for example where the company has unutilised losses.
Worked example: IRAS reviews an interest-free S$3 million loan your investment holding company extended to a related operating company for four years, and imputes arm’s length interest of S$150,000 a year. The adjustment is S$600,000 of income the lender should have recognised. The surcharge alone is S$30,000 — before any tax on the adjusted income, and regardless of whether the borrowing company’s position offsets it. The surcharge is, by design, a penalty for not doing the pricing properly in the first place.
The Safe Harbours: Where IRAS Has Already Done the Work for You
For small groups, the practical good news is that IRAS has published simple, accepted answers for the two most common related-party dealings — use them, and the pricing question largely disappears.
Routine support services: the 5% cost mark-up. Where one related company provides routine support services to another — bookkeeping, HR administration, IT helpdesk, general admin — IRAS accepts a charge of cost plus 5% as arm’s length, without benchmarking. If your holding company’s staff do the operating company’s payroll, the compliant answer is an intercompany service agreement charging the attributable costs plus 5%, invoiced and recorded like any third-party supplier.
Related-party loans up to S$15 million: the indicative margin. For related-party loans not exceeding S$15 million, IRAS publishes an indicative margin each year to be applied over an appropriate base reference rate. Adopt it, document the loan in a simple agreement, and no benchmarking study is needed. What the framework does not accept as a default is the most common SME arrangement of all: the undocumented, interest-free intercompany loan sitting in “amounts due from related company” year after year. Interest-free is a price — and usually not an arm’s length one.
For anything larger or less routine — cross-border loans beyond the threshold, IP licensing between group entities, significant goods flows — proper benchmarking is the standard, and that is specialist work.
Where Small Groups Actually Get Caught
Four fact patterns account for most of the exposure we see in owner-managed groups:
The permanent interest-free loan. Money moved from Company A to Company B years ago, booked as a related-party balance, no agreement, no interest, no repayment schedule. This is simultaneously a transfer pricing issue (imputed interest), a corporate governance issue, and — as covered in our director remuneration article — sometimes a disguised drawing. The fix is cheap: a loan agreement, the IRAS indicative margin, interest actually booked.
The unpriced management arrangement. One company’s staff run both businesses; no charge crosses between them, or a round number does, invented at year end to move profit where it is convenient. Both versions fail arm’s length. The 5% cost mark-up safe harbour exists precisely so this can be done properly with minimal effort.
The related landlord. The operating company trades from a property owned by the owner’s property-holding company, at a rent set by neither market evidence nor any evidence. Rent between related parties should be supportable against comparable market rates — agent listings for similar units are usually sufficient support at SME scale.
The new cross-border subsidiary. For readers who followed our Johor-Singapore SEZ article: the moment your Singapore company transacts with its Malaysian (or any overseas) subsidiary, you have cross-border related-party transactions examined by two tax authorities with opposite incentives. Intercompany agreements and pricing policy set on day one, as we said then, remain dramatically cheaper than remediation after either side asks questions.
A Calibrated View: What This Means at Your Size
If your gross revenue is under S$10 million: you have no formal TPD obligation, and nothing in this article requires you to commission a transfer pricing study. What the law still requires is that related-party dealings be priced defensibly — which, at this scale, the safe harbours deliver almost for free: loan agreements using the indicative margin, service charges at cost plus 5%, market-supportable rent. An afternoon of paperwork, once.
If your revenue exceeds S$10 million, or will soon: check each related-party category against the thresholds above — using the new S$2 million figure for YA 2026 — and prepare contemporaneous TPD for any category that exceeds them, in place before 30 November. If documentation was required last year, you remain in scope this year regardless of revenue.
If you have cross-border related-party flows: treat pricing and intercompany agreements as part of the structure, not an afterthought — this is the one profile where specialist transfer pricing advice earns its fee even below the documentation thresholds.
A Related-Party Health Check
- List every related-party balance and transaction in your accounts: loans, management fees, shared staff, rent, royalties, goods
- Put a written agreement behind each one — loan terms, service scope, lease
- Apply the safe harbours: IRAS indicative margin on loans up to S$15 million; cost plus 5% on routine support services
- Check gross revenue against the S$10 million TPD test — and each transaction category against the YA 2026 thresholds (S$15 million goods and loans; S$2 million services and others)
- If TPD is required, have it contemporaneous — ready before the 30 November filing, producible within 30 days of a request
- Complete the Related Party Transactions declaration with Form C where the financial-statement RPT value exceeds S$15 million
- For cross-border dealings, align the Singapore records with the overseas entity’s — the two filings must tell one story
How A1 Accounting Helps
Related-party hygiene lives inside the bookkeeping, and that is where we work. For our clients, the related-party balances are visible in the accounts we maintain every month — so we are positioned to flag the interest-free loan, paper the service charge at cost plus 5%, apply the indicative margin, and carry the whole position consistently into the financial statements, the Form C disclosures, and the tax computation due 30 November.
For groups crossing the S$10 million line, we help determine which categories actually require documentation under the YA 2026 thresholds — often fewer than feared after the S$2 million change — and for genuine cross-border or benchmarking work, we will say so plainly and bring in specialist transfer pricing support rather than stretch beyond our lane.
If your group has related-party balances that have never been formally priced, the weeks before the 30 November filing are the right time to tidy them — while it is still housekeeping, not remediation.
📞 Call or WhatsApp: +65 8066 2238 (also available on WeChat, Line & Telegram)
📧 Email: [email protected]
🌐 Visit us at: acrafilingagent.com
📍 63 Jln Pemimpin, #02-03 Pemimpin Industrial Building, Singapore 577219
Two companies, one owner is a structure. Two companies, one owner, undocumented money flows is a tax exposure. Talk to us before the November filing and we will tidy it properly.
Disclaimer: This article is for general informational purposes only and does not constitute tax advice. Transfer pricing obligations, documentation thresholds and safe harbours depend on individual circumstances and the current IRAS Transfer Pricing Guidelines, which are revised periodically. Consult a qualified tax professional and refer to IRAS at iras.gov.sg before acting.